The global shipping industry is ordering alternative-fuel vessels faster than ports can develop the infrastructure needed to fuel them, according to a new report from Lloyd’s Register (LR), highlighting a growing challenge for shipowners investing in cleaner propulsion technologies.
LR’s new Fuel for Thought: Ports report, released Monday, found that 1,942 alternative-fuel-capable vessels were on order as of January 2026, representing 47% of the global orderbook by tonnage, according to Clarksons Research.
But the infrastructure needed to support those ships varies dramatically depending on the fuel.
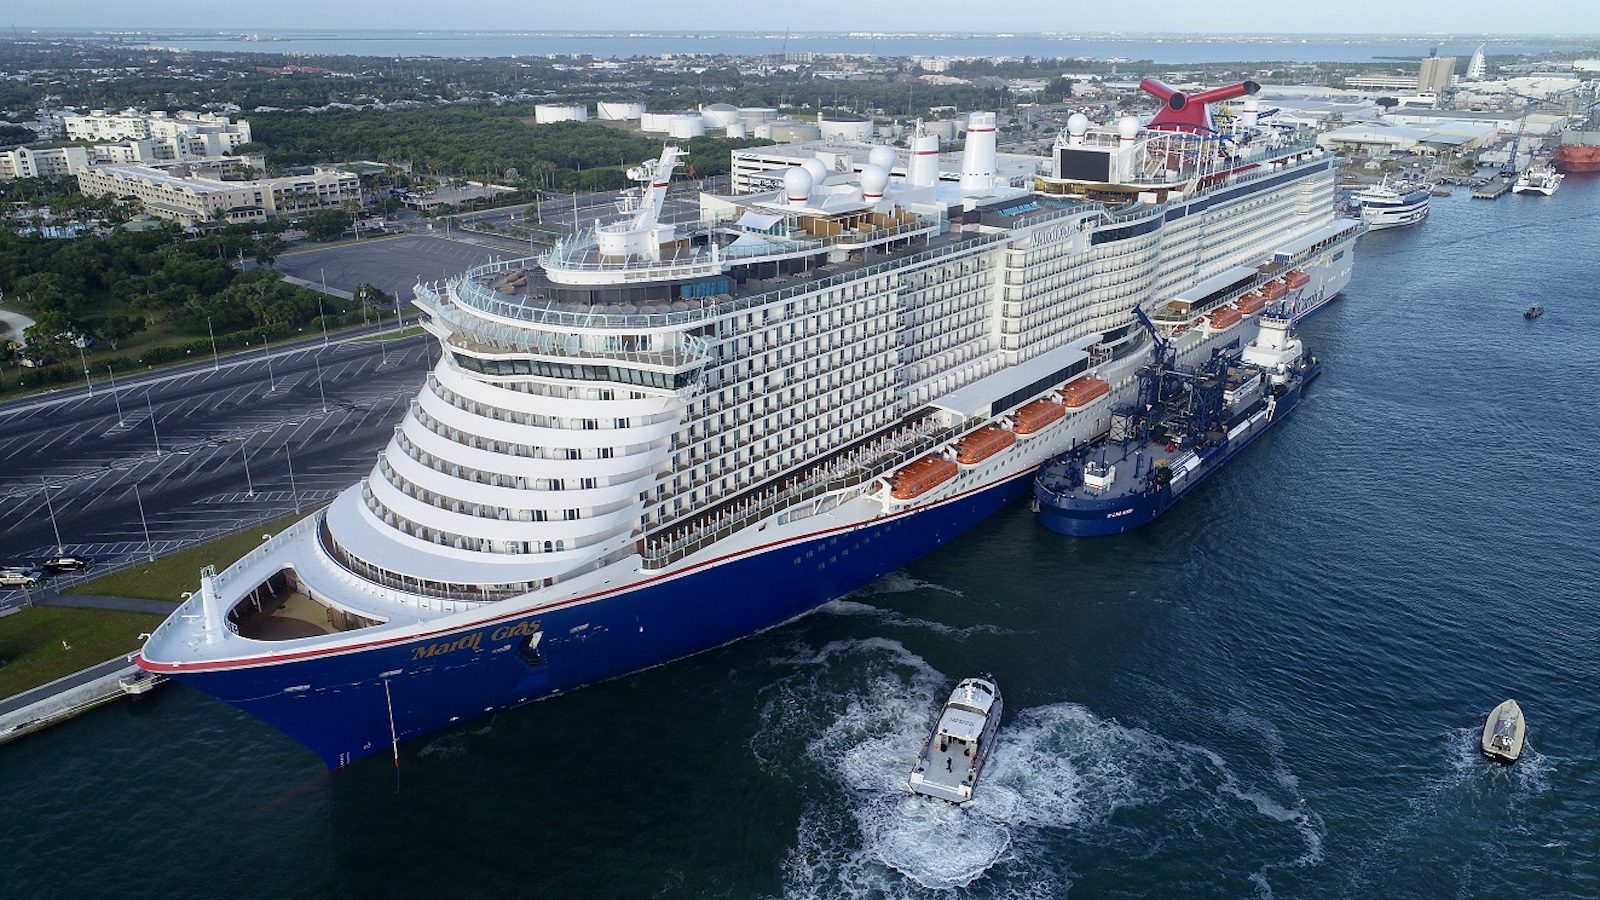
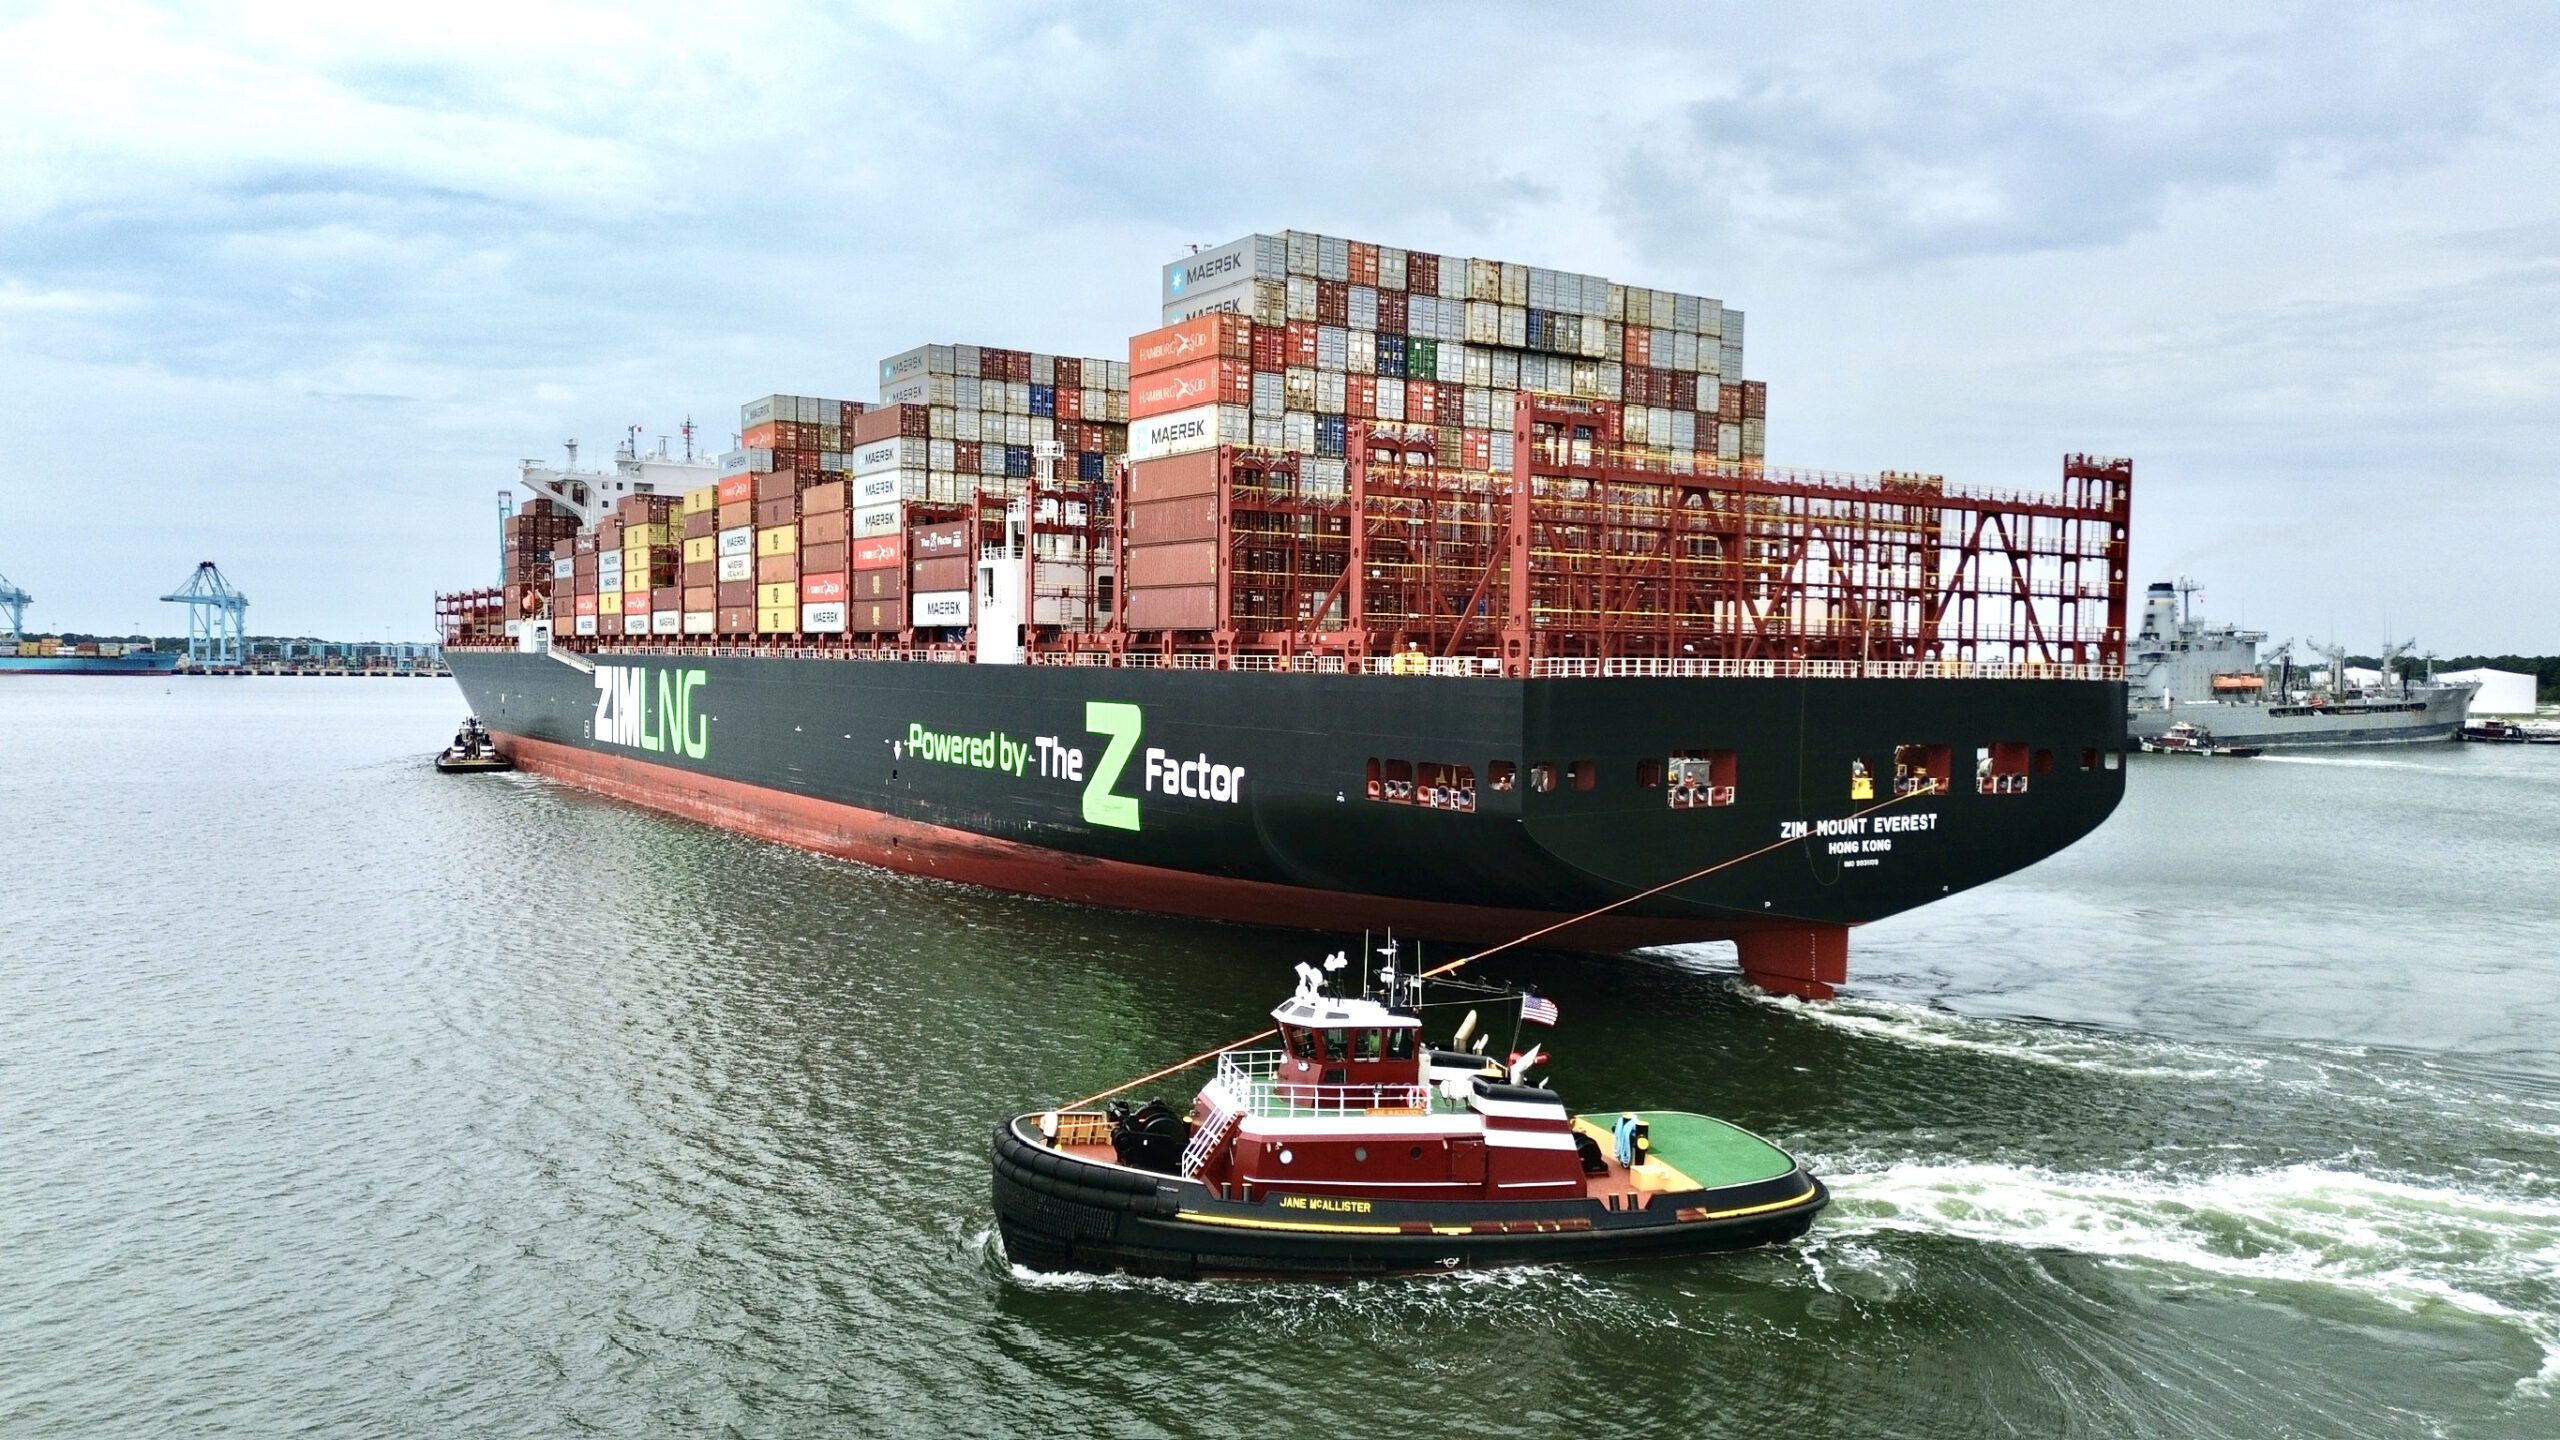
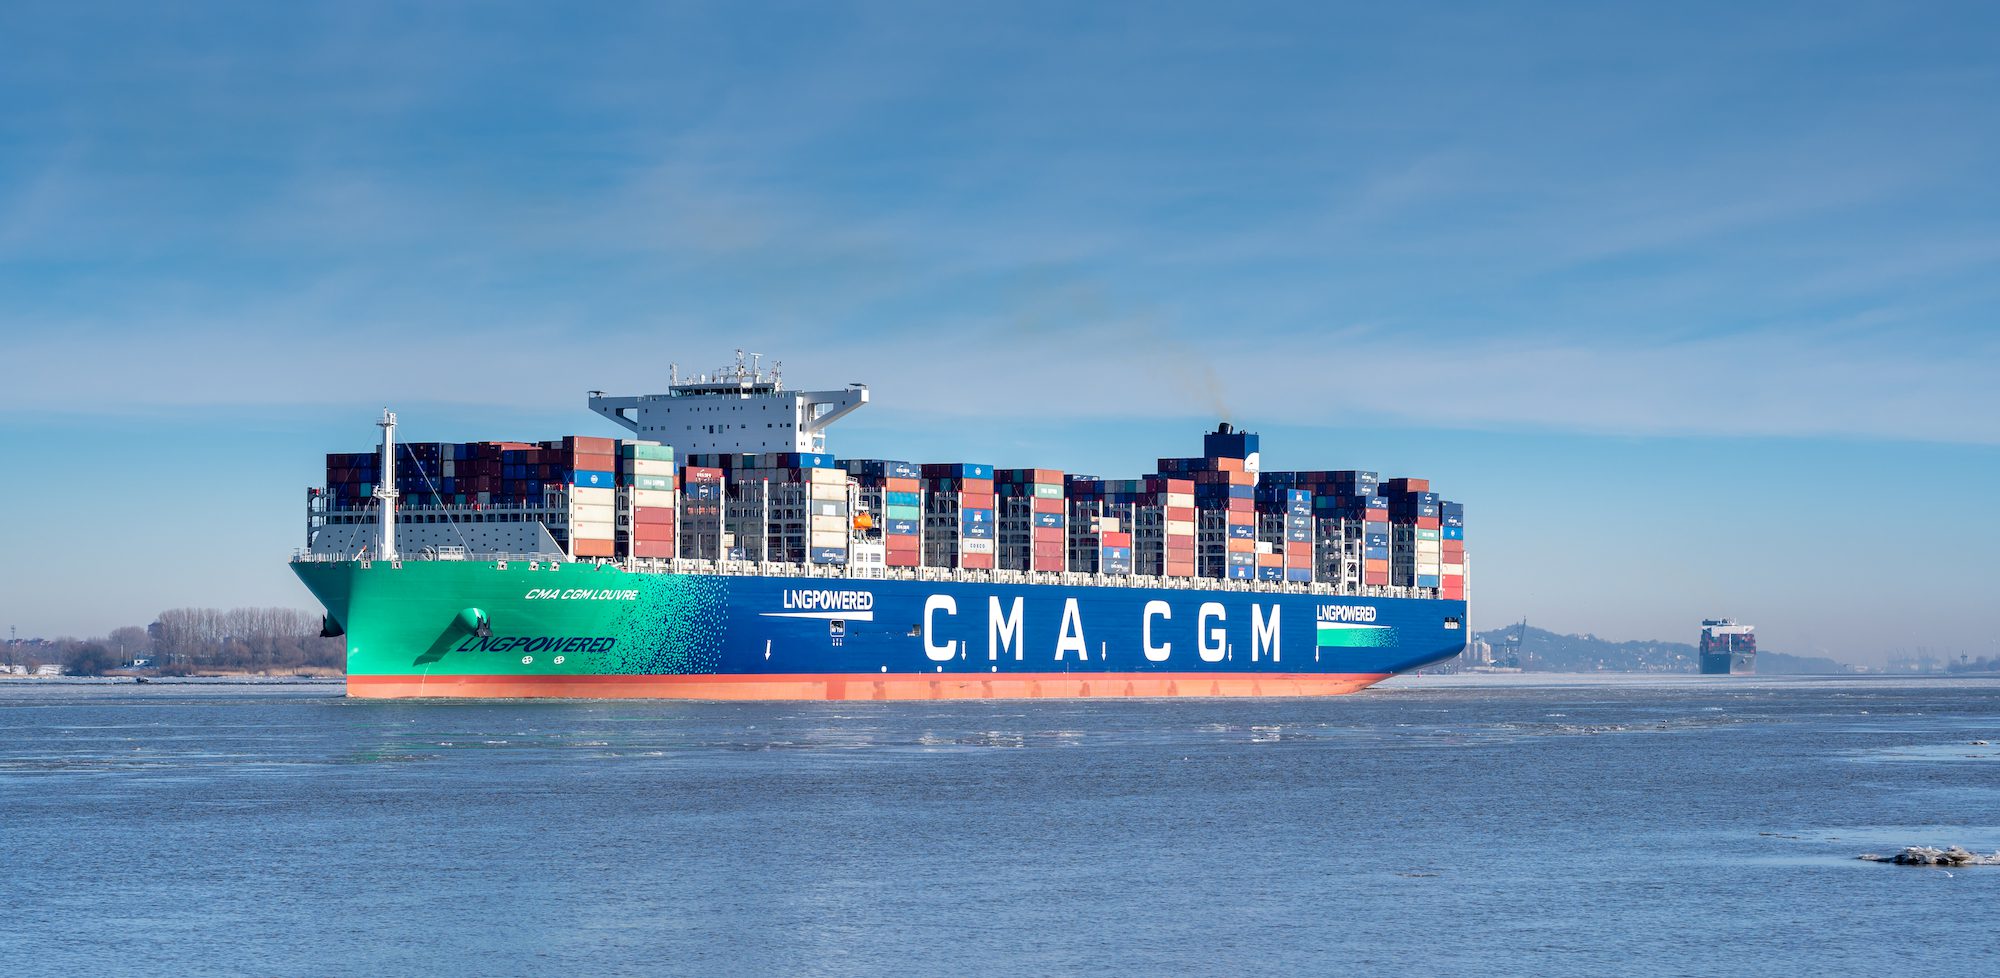
Liquefied natural gas (LNG) bunkering was available at 222 ports worldwide, compared with just 25 ports actively offering methanol. Commercial ammonia bunkering, meanwhile, has been recorded at only one port, following the first operation at Ulsan, South Korea, in April 2026.
The disparity is particularly significant given that shipowners have ordered 385 methanol-capable vessels and 45 ammonia-capable ships, according to LR.
“The fleet is moving faster than the infrastructure needed to support it,” said Kamran Ul Haq, Senior Vice President of LR Ports Advisory. “An owner can order an alternative-fuel vessel today, but that does not mean the fuel will be available where that ship needs it. Fuel strategy and trading strategy can no longer be considered separately.”
The findings come amid a renewed surge in alternative-fuel vessel orders, led overwhelmingly by LNG.
As gCaptain reported in October, data from DNV’s Alternative Fuels Insight platform showed that shipowners ordered 69 alternative-fuel vessels in September, the highest monthly total in nearly two years. LNG accounted for 48 of those orders, with new contracts spanning containerships, car carriers, bulk carriers and ro-ro vessels.
The surge brought alternative-fuel orders to 311 vessels through the first nine months of 2026, up 53% from the same period a year earlier.
LNG’s dominance reflects its relative maturity compared with emerging alternatives. With an established global supply network and commercially proven propulsion technology, LNG offers shipowners greater flexibility when deploying vessels across international trading routes.
Methanol, by comparison, is gaining ground at major bunkering hubs but remains limited in geographic reach. Ammonia is still at an earlier stage, with most ports pursuing the fuel focused on pilot projects, safety assessments and regulatory frameworks.
The challenge is particularly relevant for ports deciding where to invest.
Last week, gCaptain reported that the ports of Los Angeles and Long Beach identified LNG and methanol as the most viable alternative marine fuels for the near and medium term.
Their joint Clean Marine Fuel Feasibility Assessment recommended a phased approach to infrastructure development, relying on existing ship-to-ship bunkering capabilities for LNG while pursuing methanol pilot projects and improvements to safety and permitting requirements.
The Southern California findings closely mirror LR’s conclusion that ports should focus on fuels with credible demand rather than attempt to accommodate every emerging technology.
“Ports do not need to back every fuel,” Ul Haq said. “They need to understand where credible demand will emerge and put the safety, regulation, skills and partnerships in place to respond.”
LR also found that alternative-fuel infrastructure remains concentrated in a relatively small number of shipping hubs, particularly Northern Europe, North Asia and Singapore. That concentration makes access to fuel along specific trade routes increasingly important when owners evaluate newbuildings and vessel conversions.
Biofuels offer a more immediate alternative because compatible blends can generally be supplied through existing bunker infrastructure. LR’s Fuel Oil Bunker Analysis and Advisory Service recorded drop-in biofuel deliveries at 90 ports over the previous 12 months, although the 13 leading ports accounted for 77.5% of recorded quantities. Singapore alone represented more than a quarter.
Hydrogen, meanwhile, remains largely confined to demonstration projects and short-sea applications.
The report also underscores the distinction between making alternative fuels available and ensuring they deliver meaningful emissions reductions.
As gCaptain recently examined, LNG’s rapid adoption has brought increased scrutiny of methane slip, the unburned methane released from ship engines, particularly as European emissions regulations place greater financial consequences on greenhouse gas performance.
The climate benefits of methanol and other emerging fuels likewise depend heavily on how they are produced, making the availability of genuinely low-carbon fuel supplies another challenge beyond bunkering infrastructure.
For ports, LR says the next phase of the transition will depend on targeted investment, regulatory readiness and closer coordination with shipping companies and fuel suppliers.
Berth-specific risk assessments, licensing, emergency response capabilities and workforce training will be essential to moving alternative fuels from trials into routine commercial operations.
“For ports, investment should follow credible demand rather than trying to prepare for every fuel at once,” Ul Haq said. “Named vessel programmes and green shipping corridors are also ways to reduce infrastructure risk, alongside early investment in safety frameworks, licensing, emergency preparedness and workforce skills.”
The central message for shipowners is that ordering a vessel capable of burning an alternative fuel is only part of the transition. Ensuring that fuel will be available, affordable and commercially viable along the ship’s intended trading routes is becoming just as important.
 Join The Club