By Paul Morgan (gCaptain) –
For most of shipping history, the valuation equation has been straightforward. A ship leaves the yard, begins ageing and progressively loses value. New steel commands the premium. Older steel trades at a discount.
The VLCC market has just turned that logic on its head.
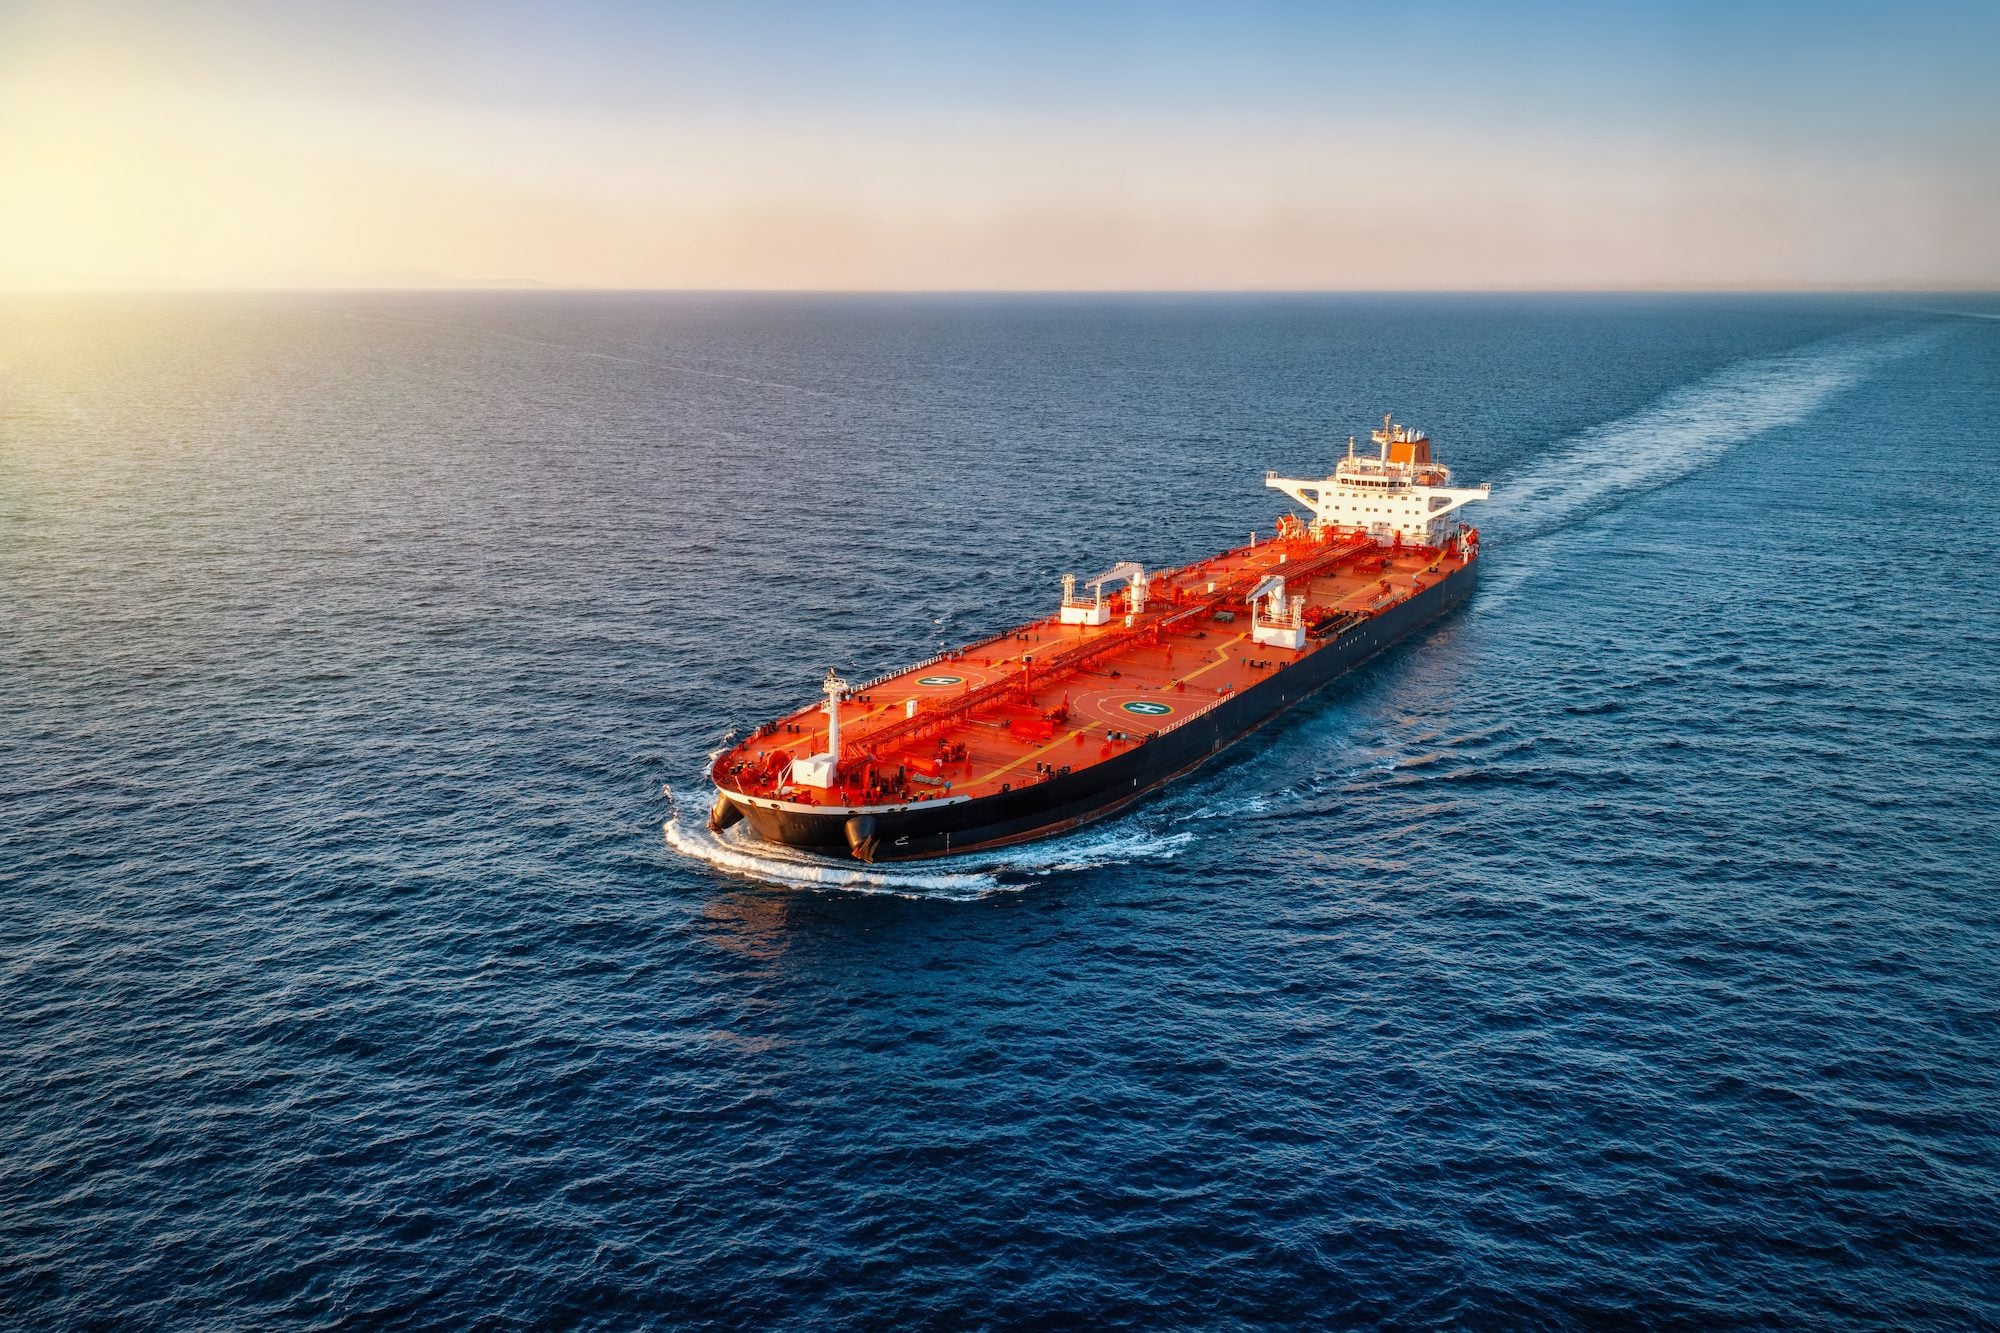
Several very large crude carriers built before 2016 have recently been reported sold for $150 million or more, while the average price quoted for ordering a new VLCC has been around $135 million. More remarkably, shipbroker Braemar says ten-year-old VLCC values have moved above newbuilding prices for the first time in its records.
This is no longer simply a case of buyers paying a premium for an almost-new resale vessel. The distortion has travelled deep into the age profile of the world tanker fleet.
Figures from Xclusiv Shipbrokers demonstrate just how rapidly it has happened. Between 10 July and 18 September, the assessed value of a five-year-old VLCC increased from around $145 million to $172 million, a rise of approximately 18.6 per cent. Ten-year-old tonnage climbed from $115 million to $152 million, around 32 per cent.
The extraordinary figure is at 15 years. Values increased from approximately $83.5 million to $135 million in little more than two months, a rise of about 62 per cent.
A 15-year-old tanker can therefore be worth approximately as much as ordering a new ship. The explanation is not that a 15-year-old vessel has somehow become technically equivalent to a newbuilding. It clearly has not.
What buyers are paying for is time. A vessel already afloat can start earning immediately. A vessel ordered from a shipyard exists initially as a contract, a construction slot and a future delivery date. In today’s tanker market, that difference can be worth tens of millions of dollars.
$200 Million for Immediate Availability Nothing illustrates the phenomenon better than the reported sale of Pinios. The 306,000 dwt, scrubber-fitted VLCC was delivered from China’s Hengli Heavy Industries to Dynacom in 2026. Dubai-based Onex DMCC has subsequently been linked to its purchase for around $200 million, with the vessel renamed Promise.
The reported price is extraordinary. VesselsValue had assessed the ship at approximately $179.4 million. The buyer therefore appears to have been prepared to pay a premium exceeding $20 million over that valuation for access to near-new VLCC tonnage without waiting for a future shipyard delivery.
Nor is this an isolated example at the younger end of the fleet. Pantheon Tankers has reportedly sold the 2011-built, 314,000 dwt Sea Leopard for around $135 million. Clarksons had put a benchmark new VLCC at approximately $131 million at the beginning of September.
Think about what that means. A vessel already around 15 years into its commercial life has reportedly achieved more than the headline price of contracting its replacement. From a conventional asset-depreciation perspective, it makes little sense. From today’s earnings perspective, it makes considerably more.
When a VLCC Earns Hundreds of Thousands a Day
The Baltic Exchange VLCC average reached approximately $722,946 per day on 18 September. In mid-September 2025, the comparable figure was around $79,700. That represents an increase of more than 800 per cent in twelve months.
Even more dramatic figures have appeared on individual routes. The Baltic Exchange’s TD3C assessment for the Middle East Gulf-to-China trade moved through the equivalent of $1 million per day during September, something previously almost unimaginable in normal tanker trading.
Those headline assessments require care. A benchmark time-charter-equivalent calculation is not necessarily the same as cash actually earned by every vessel. Individual fixtures depend on Worldscale, voyage costs, positioning, insurance, waiting time and, crucially, whether the ship is prepared to transit the Strait of Hormuz.
Nevertheless, the underlying message is undeniable. VLCC earnings have reached exceptional levels.
Once a ship can generate hundreds of thousands of dollars a day, paying another $20 million or $30 million to obtain it immediately rather than several years from now becomes commercially understandable.
Availability itself has acquired a price. Hormuz Changed the EquationThe Strait of Hormuz is central to understanding why.
Iran’s closure of the strait on 2 March caused Middle East-to-Asia VLCC rates to reach their highest level since at least November 2005, when the US Energy Information Administration’s data series begins.
The mechanism is straightforward. Ships unable or unwilling to transit the area disappear from the effective trading fleet. Vessels delayed inside or outside the Gulf are also effectively removed from available capacity. Alternative crude sourcing increases voyage distances. Longer voyages increase tonne-mile demand.
The world does not necessarily need to consume more oil for tanker demand to increase. It needs that oil to travel farther. War-risk insurance has magnified the effect.
Additional war-risk premiums for Hormuz transits climbed during the crisis to levels reported at 7.5 to 10 per cent of hull value in particularly high-risk circumstances. On a $100 million ship, that can mean millions of dollars of additional insurance cost for a voyage.
Yet extremely high VLCC freight earnings mean crude carriers can sometimes absorb costs that would make the same voyage commercially impossible for a smaller tanker earning much less.
The result is an extraordinary market in which geopolitical risk is simultaneously restricting ship supply and increasing the value of ships willing and able to trade.
Oil Producers Want Their Own Ships
Another important change is taking place on the buying side. National oil companies have powerful reasons to secure their own transportation capacity rather than depend entirely upon third-party shipowners prepared to enter high-risk areas.
ADNOC Logistics & Services announced in August that it was acquiring six modern secondhand VLCCs alongside five VLGCs in an overall $1.3 billion fleet investment. The six VLCC acquisitions take its VLCC fleet to 14.
The company specifically highlighted the near-term operational and earnings potential of acquiring vessels that could enter service rapidly. That distinction matters. For a national oil company, tanker ownership is not simply an investment in shipping. During severe disruption it can become part of the security of the export chain.
Trading companies have also been active. Onex has been linked through broker reports and sales registers to at least five VLCC acquisitions, while other established tanker buyers have been competing aggressively for available ships.
They are all chasing something shipyards cannot manufacture quickly enough: immediate capacity. But the Shipyards Will Eventually Catch Up
There is, however, a substantial warning hidden inside today’s extraordinary valuations. Shipowners are ordering VLCCs aggressively. According to Veson Nautical, 183 VLCCs were ordered during the first half of 2026, compared with just 18 during the equivalent period of 2025. Those ships will eventually enter the fleet.
That creates a fundamental difference between today’s earnings market and the long-term asset market. A secondhand buyer paying $150 million for ageing tonnage is effectively making two bets.
The first is that exceptional earnings will continue long enough to recover the acquisition premium. The second is that the ship will retain sufficient residual value when the geopolitical and freight environment eventually normalises. Neither is guaranteed.
A 15-year-old VLCC remains a 15-year-old VLCC regardless of its market price. Steel condition, coatings, cargo systems, machinery reliability, survey status and drydocking expenditure do not disappear because freight rates are high.
At this age the vessel is also approaching the period in its life when condition, maintenance history and future capital expenditure become increasingly important.
When earnings are several hundred thousand dollars a day, buyers may tolerate those liabilities. At $50,000 a day, they may look very different. Shipping Has Put a Price on Time That is what makes the present VLCC market so unusual.
It is tempting to describe it simply as a tanker boom, but something more interesting is occurring. The market has temporarily separated the price of a ship from the conventional relationship between age and replacement cost.
A newbuilding may have newer machinery, fresh coatings, lower maintenance requirements and decades of remaining commercial life.
What it does not have is availability today, and today has become extremely expensive.
Eventually, new tonnage will arrive. Freight markets will change. Hormuz may stabilise. Insurance premiums may fall. Effective tanker supply may recover.
When that happens, traditional valuation fundamentals are likely to matter again. For now, however, the VLCC market has demonstrated one of shipping’s oldest commercial realities in unusually dramatic fashion.
A ship is not worth simply what it cost to build, what its steel is worth, or how many years remain before recycling. It is worth what somebody needs it to do.
And in September 2026, the most expensive capability in the tanker market is remarkably simple: being available now!
 Join The Club