Logistics software provider Descartes Systems Group has released its April Global Shipping Report, revealing a significant increase in U.S. container import volumes in March 2023 compared to February 2023, keeping the monthly trend-line aligned with pre-pandemic 2019 volumes.
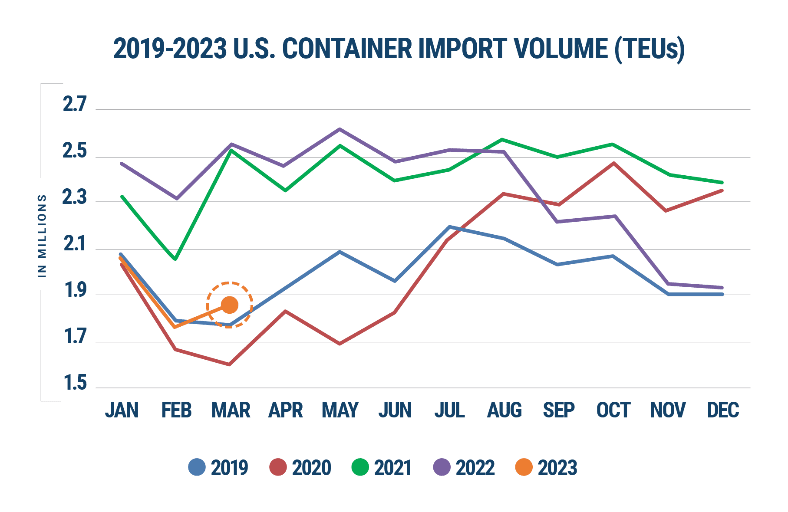
According to the data collected by Descartes’ global trade software Descartes Datamyne, the March 2023 U.S. container import volumes increased by 6.9% from February 2023 to 1,853,705 TEUs, mainly driven by gains at the Ports of Los Angeles and Long Beach.
Descartes said to keep in mind that March 31 days versus 28 for February and, with the Chinese Lunar New Year holiday occurring in January 2023, there still could be some impact on container import volumes in early March 2023.
Although March TEU volume was down 27.5% from the same month last year, it was up 4.2% from pre-pandemic March 2019.
Despite overall increases, the Descartes’ report shows that port transit delays for all ports had stabilized latest. Meanwhile, the West Coast labor situation still poses a risk to port operations.
Credit: Descartes
“Container import volumes at the Ports of Los Angeles and Long Beach have been in decline, but in March they experienced significant increases. 2023 continues to track 2019 volumes,” said Chris Jones, EVP Industry and Services at Descartes. “There was also good news in that the port transit delay times remained constant despite the significant volume increases.”
The report also highlighted that imports from China continue their downward trend. In March 2023, Chinese imports declined with a decrease of 7.4% to 586,129 TEUs—down 41.6% from the August 2022 high. China represented 31.6% of the total U.S. container imports in March, a decline of 4.9% from February and 9.9% from the high of 41.5% in February 2022.
Moreover, West Coast ports made strong gains at the expense of smaller ports. The fact that there is still no change in the labor situation presents continued risk to West Coast port operations. However, top West Coast ports increased their market share of imports to 43% in March, up 7.0% versus February. Of the total import container volume, top East and Gulf Coast ports increased market share slightly to 47.4%, up 0.9% compared to February.
Descartes also released its 2023 U.S. Ports Report, providing a deeper examination of import and export data for 2022, YoY comparison of monthly TEUs, top carriers and consignees, and top countries of origin at each port.
Key findings in the report showed that 2022 U.S. imports didn’t mark a return to traditional trade patterns, nor did they meet early expectations of YoY growth, declining -3.42% vs. 2021. While only six of the Top 30 U.S. ports saw declines in throughput in 2021, 12 ports posted fewer TEUs YoY in 2022 (mainly a result of the supply chain crunch). All West Coast ports posted YoY declines in volume, with two exceptions: Portland, Oregon and Port Hueneme, California.
The ports report also showed that for much of 2022, port transit delays were coming in at 10+ days, but by January of this year the situation improved, mainly due to reduced volumes and improved container processing at major ports.
The Port of Los Angeles remained the busiest port in the country for container imports last year despite an overall 14% year over year drop in imported volumes. Meanwhile, the Port of New York and New Jersey surpassed the Port of Long Beach to become the second busiest port for container imports, with a 3.8% gain in TEUs reflecting shifting trade patterns.
The Port of Los Angeles reported its best single month in its history. In a media briefing, port executive director Gene Seroka announced the port processed 1,042,652 TEUs, 23k TEUs more than the July 2025 record.
U.S. container imports are finally beginning to slow after an unusually long peak shipping season that stretched through the summer and into early fall, according to the latest Global Port Tracker report from the National Retail Federation (NRF) and Hackett Associates. The slowdown comes after months of stronger-than-expected cargo volumes at major U.S. ports, as retailers continued bringing in merchandise despite tariffs, inflation and higher transportation costs. Ports covered by Global Port Tracker handled 2.3 million twenty-foot equivalent units (TEUs) in August, up 0.4% from July but down 0.7% from a year earlier. August now appears to have been the busiest month of 2026, marking a shift from last month’s forecast that September would take the top spot. “Even with any fluctuations in final data, we’re likely past the busiest part of the year,” said Jonathan Gold, NRF vice president for supply chain and customs policy. “The truth is that the peak season started early and was stretched out through the summer and early fall, with the difference from month to month often amounting to little more than a rounding error,” Gold said. The latest forecast puts September imports at 2.28 million TEUs, down from the 2.31 million TEUs projected a month ago. October is expected to ease further to 2.25 million TEUs before volumes fall to 2 million TEUs in November. Despite the expected slowdown, imports are still running well ahead of last year in some months. September volumes are forecast to rise 8.2% year over year, followed by an 8.5% increase in October. The revised outlook follows a peak season that has repeatedly defied expectations. Retailers moved merchandise into the country earlier this year to get ahead of tariff changes and supply chain uncertainty, initially raising expectations that imports would peak early and decline through the summer. Instead, volumes remained elevated, with shipping delays and resilient consumer demand helping extend the traditional peak season. The strength has been evident at individual ports. The Port of Los Angeles recorded its busiest three-month stretch on record during June, July and August, while the Port of Savannah reported a record September earlier this week, handling 504,015 TEUs, up 3.7% from a year earlier. Hackett Associates founder Ben Hackett said the economic outlook remains mixed, with consumers continuing to spend despite signs of weakening confidence. “Despite this, consumers appear to remain confident and cautious at the same time, with consumer confidence indexes sliding to multi-year lows while consumer spending continues to be robust in the face of increasing inflation,” Hackett said. For the full year, Global Port Tracker now expects imports at major U.S. container ports to reach 25.8 million TEUs, up 1.4% from 25.4 million TEUs in 2025. That is slightly above last month’s forecast of 25.7 million TEUs. Looking ahead, January 2027 imports are forecast at 2.07 million TEUs, down 1.9% year over year, followed by 1.92 million TEUs in February, up 1%. For retailers, the extended shipping season means much of the merchandise needed for the holidays is already in the country, reducing the need for another major import surge before year-end. “Most holiday merchandise has arrived, and the remainder of the year is just a matter of last-minute replenishment and preparation for early 2027,” Gold said.
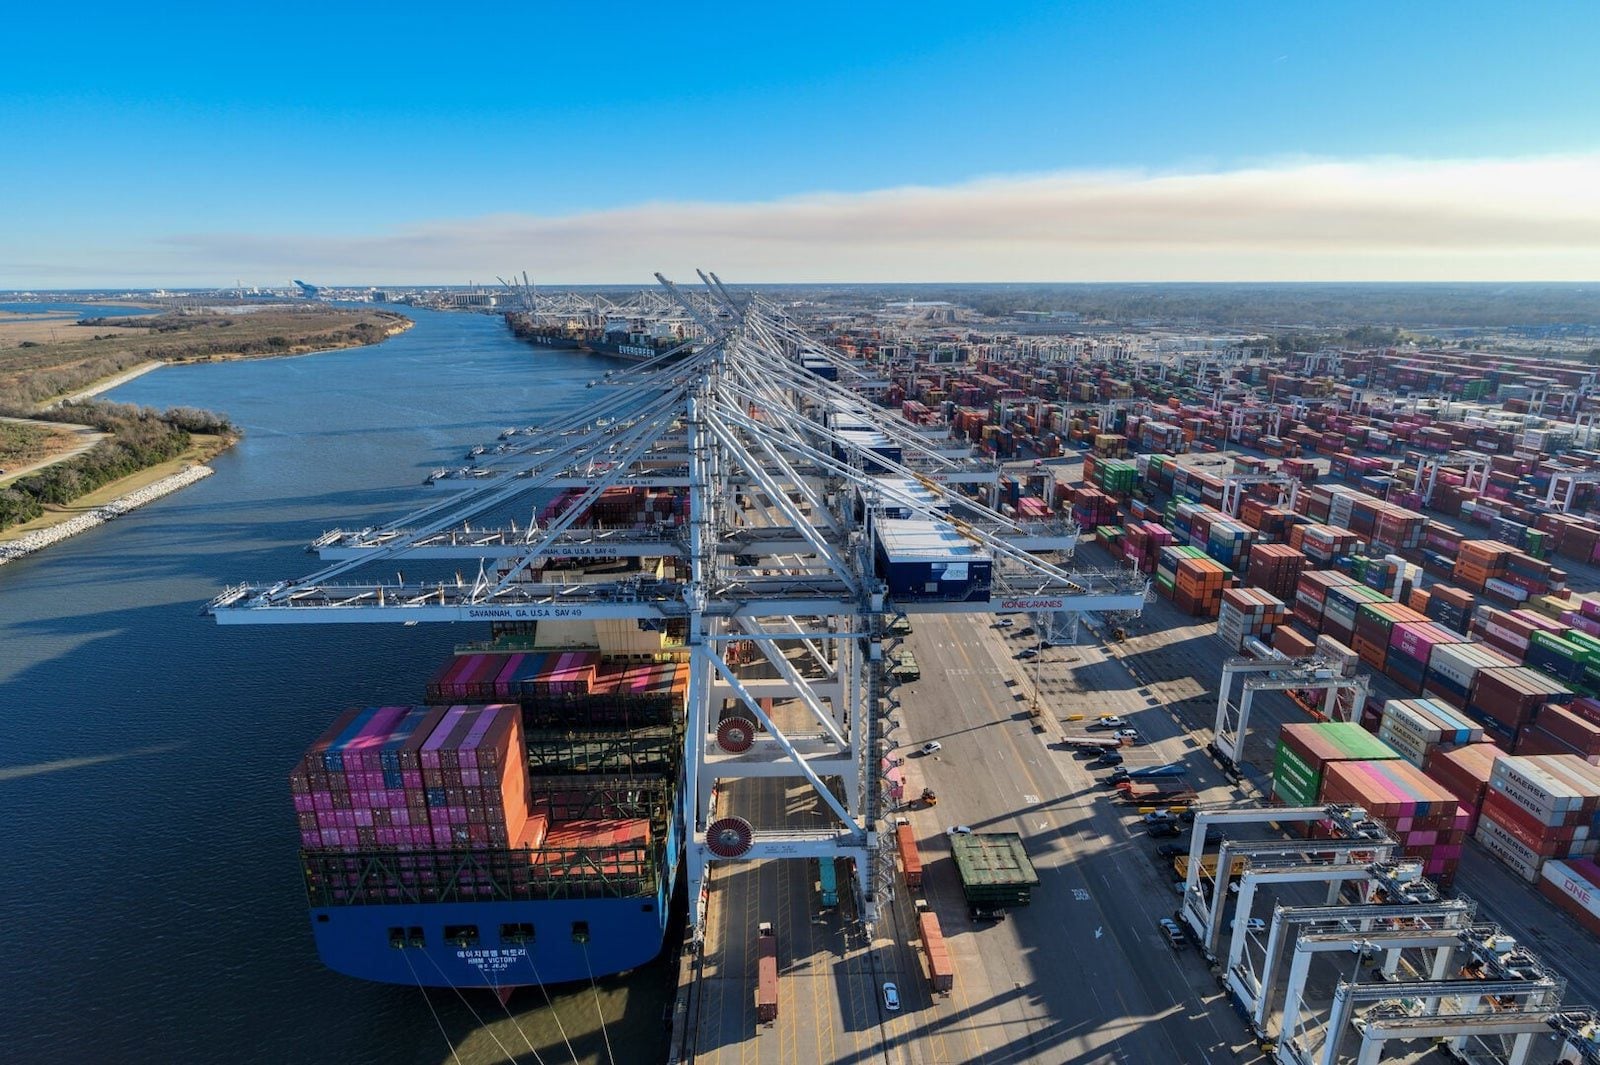
The Port of Savannah handled a record 504,015 twenty-foot equivalent units in September, up 3.7% from a year earlier as strong imports and a later-than-usual peak season boosted volumes.
October 7, 2026
Total Views: 630
Get The Industry’s Go-To News
Subscribe to gCaptain Daily and stay informed with the latest global maritime and offshore news
— just like 106,954 professionals
Secure Your Spot
on the gCaptain Crew
Stay informed with the latest maritime and offshore news, delivered daily straight to your inbox
— trusted by our 106,954 members
Your Gateway to the Maritime World!
Essential news coupled with the finest maritime content sourced from across the globe.
 Join The Club